Whether you’re a student, a young professional, or someone working in a new city, living in a PG or rented flat is common in India. While this lifestyle offers flexibility, it can also raise questions when you apply for a personal loan or any other type of credit. Lenders often look beyond income and employment—they also consider your living arrangement as part of the bigger picture.
Why Do Lenders Care About Your Living Situation?
When you apply for a loan, lenders want assurance that you are financially stable and likely to repay on time. Your residential status plays a role in how they perceive your stability.
PG Accommodation
Living in a paying guest facility is usually associated with students, freshers, or individuals with short-term stays. This may give lenders the impression that you’re still establishing financial independence.
Rented Flats
Renting a flat shows slightly more stability than PG accommodation, but it still comes with monthly rental commitments. Lenders evaluate whether these commitments leave you with enough disposable income to manage EMIs.
Key Factors Lenders Assess
1. Proof of Address
Lenders require valid proof of address for KYC verification. Suppose you live in a PG or a rented flat, utility bills or rent agreements may be needed to establish residence. Any mismatch in documents could delay or reject your application.
2. Stability of Residence
Frequent changes in address can raise red flags for lenders. A stable residence history—such as living in one flat for more than a year—helps build confidence in your reliability.
3. Income-to-Rent Ratio
If a large portion of your salary goes toward rent, lenders might consider you at higher risk. They calculate your debt-to-income ratio, which includes rent plus potential EMIs, to decide your eligibility.
4. Employer and Job Stability
For people in PGs or rented flats, lenders give more weight to steady employment. A strong employer profile and regular salary credits often outweigh concerns about rented accommodation.
5. Credit Score and History
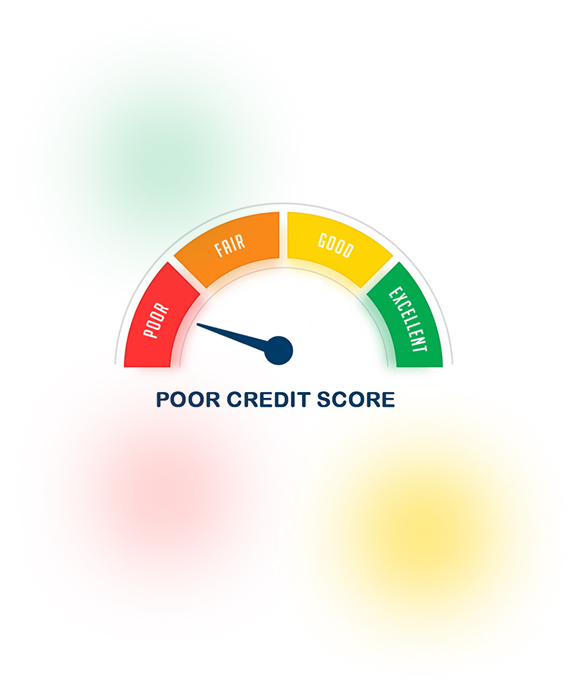
Regardless of where you live, your credit report carries the most weight. A high credit score (750+) can help offset any doubts lenders may have about your residential status.
Tips to Strengthen Your Loan Application While Living on Rent
- Keep Documentation Ready:Maintain a proper rental agreement and updated address proof.
- Show Job Stability: Highlight consistent employment and salary history.
- Maintain a Good Credit Score:Pay EMIs and credit card bills on time.
- Limit Debt and Rent Burden: Avoid having too many ongoing loans if rent already takes a big chunk of income.
- Consider a Co-Applicant: If possible, applying with a family member who owns property or has a strong credit profile can improve approval chances.
Conclusion
Living in a PG or a rented flat doesn’t stop you from getting a loan, but it does influence how lenders view your financial stability. By keeping your documents in order, demonstrating stable income, and maintaining a strong credit score, you can improve your chances of approval. Remember, lenders are more interested in your repayment ability than your address—so focus on building a solid financial profile, and you can secure a loan no matter where you live.