People still talk about closing personal loans, but many get it wrong right from the start. Borrowers often think the loan ends for good once that last EMI goes through. That is not the case, though. Without getting a formal No Dues Certificate, or NDC, which some call a No Objection Certificate or NOC, the whole thing stays unfinished in the credit world. It does not get recorded properly.
This creates real problems down the line. Accounts might have tiny unpaid bits left, like extra interest or forgotten fees that build up quietly. Lenders sometimes mess up reporting the closure to credit bureaus. Those small issues could turn into defaults on your record. Your credit score takes a hit months or years later. That makes it harder to get new loans when you need them.
What Is a No Dues Certificate (NDC)?
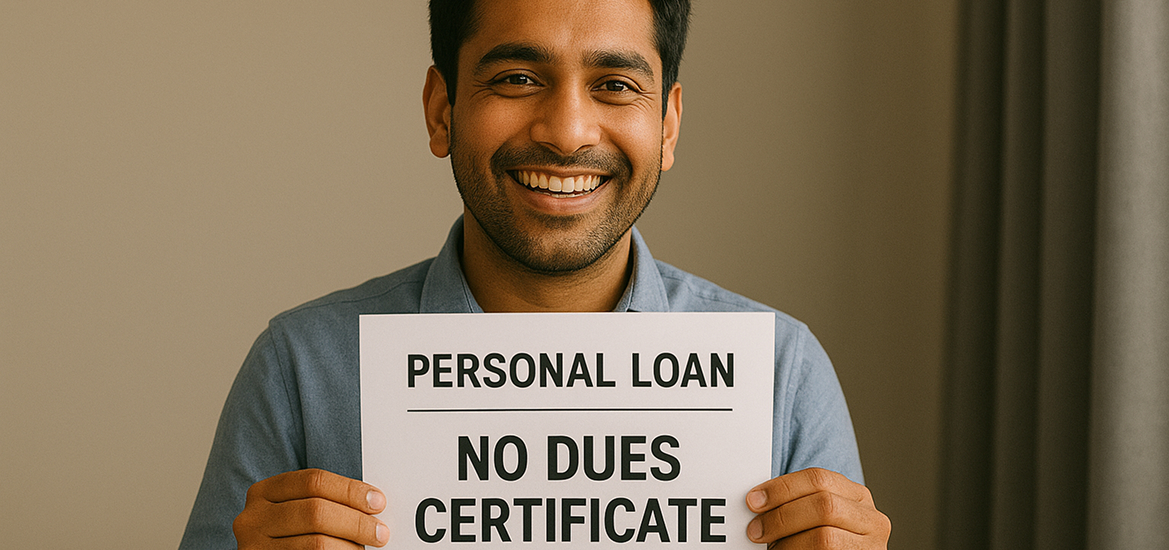
The No Dues Certificate, or NDC, goes by NOC, too, in some places. It is a key legal document from the lender to the borrower. Lenders give it out to show that the borrower paid everything back. That includes the main amount, all interest, and any extra fees tied to the loan. It proves the account is settled for good.
Banks, NBFCs, or housing finance companies issue the NDC right after the balance hits zero. They finish all the paperwork, too. This document means the loan relationship ends legally. For borrowers, it matters a lot. You need it to clear any hold on assets, like removing a lien from your car or property mortgage. It also makes sure credit bureaus update your report to show the loan as closed.
Why Your NDC Is Essential After Personal Loan Closure?
Your NDC really matters once the personal loan wraps up.
- First off, it confirms every single EMI got paid in full. The lender puts it in writing that they received the principal, interest, and all installments. No questions left about what you owe. The loan agreement ends clean.
- It also makes sure the closure gets reported right to credit bureaus like CIBIL or Experian. The NDC tells them to change the status to closed or settled with no balance. Without it, the loan might stay listed as active or open. That hurts your chances for future credit.
- The certificate stops hidden charges from messing with your score, too. It verifies that the balance is zero. Things like leftover interest or small fees get caught early. Otherwise, they might turn into defaults later on. The NDC blocks those kinds of claims.
- You get protection from collection calls even after closure. Errors happen sometimes with lenders or their agents. They might keep chasing you by mistake. Show the NDC, and it stops all that right away for that loan.
- When you go for a new loan, like a home one, the NDC helps a ton. Lenders want proof that old debts are paid. It speeds things up in their checks. They see your good payment history. Risk looks lower to them.
Common Mistakes Borrowers Make After Loan Closure
Borrowers often make critical errors right after paying off a loan, assuming the process is complete. These mistakes can silently lead to credit score issues and complications years later because the loan closure wasn't officially recorded or verified. Such mistakes are:
- Throwing away old EMI receipts
- Not downloading the NDC immediately
- Assuming auto-debit removal is automatic
- Not checking the credit report after closure
- Not keeping written proof
Conclusion
Borrowers mess up a lot after paying off loans. They figure it is all over and move on. That leads to credit problems years later. The closure never got official. One big mistake is tossing out those old EMI receipts. Another is not grabbing the NDC as soon as possible. People assume the auto-debit stops on its own. They skip checking the credit report afterward. Keeping no written proof seals the trouble.
Paying the last EMI just closes it for you personally. The financial system needs more. The lender has to issue the NDC. They update the credit bureau to closed status. That step guards your score from fee fights. It ends your duties legally. Your record stays clean for easy borrowing ahead.